Meaning
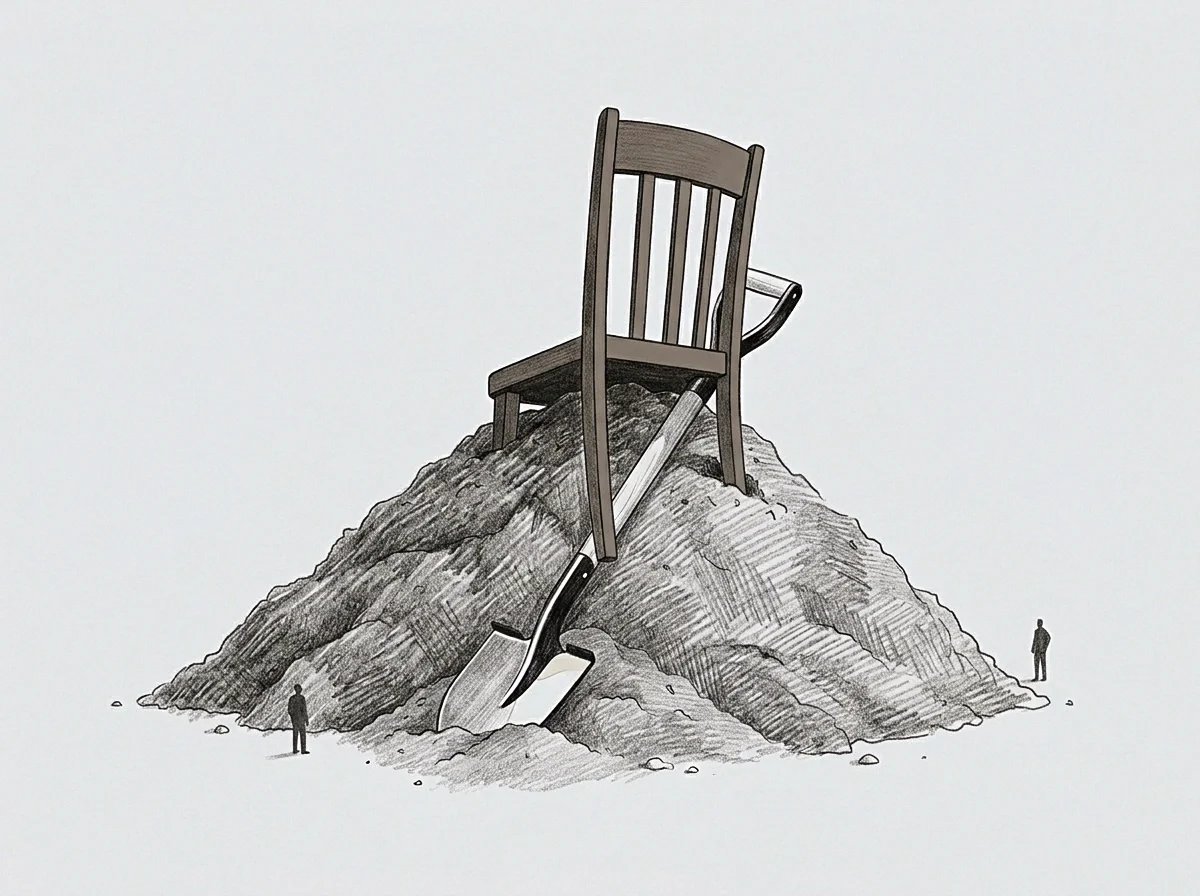
Financial obligations that do not appear on an official balance sheet represent a latent claim against future assets. An unrecorded liability often stems from verbal agreements or pending legal actions that have not yet been quantified. It poses a risk to the valuation of a company because it represents a debt that will eventually need to be paid.
Identifying these hidden costs is a primary task during any due diligence process.
Hidden Debt
Sources of these obligations include unpaid taxes, employee bonuses, warranties, or legal fees that have not been accounted for. An unrecorded liability might also take the form of an informal promise to grant equity to an early advisor. Because there is no formal entry in the accounting system, these items are easy to overlook.
They often surface only when a new investor or buyer examines the records in detail. The cost of settling these claims can drastically reduce the net worth of the founders.
Omission Risk
Failing to disclose these items can lead to accusations of fraud or breach of contract. An unrecorded liability makes it impossible to calculate the true burn rate or runway of a business. It creates a gap between the perceived health of the firm and its actual financial position.
Discovery Process
Auditors use interviews and bank statements to find evidence of these missing entries. Every unrecorded liability that is found must be added to the official books to provide an accurate picture. The removal of these shadows is necessary for a successful exit.
A clean record requires that every potential expense be acknowledged and measured.