Meaning
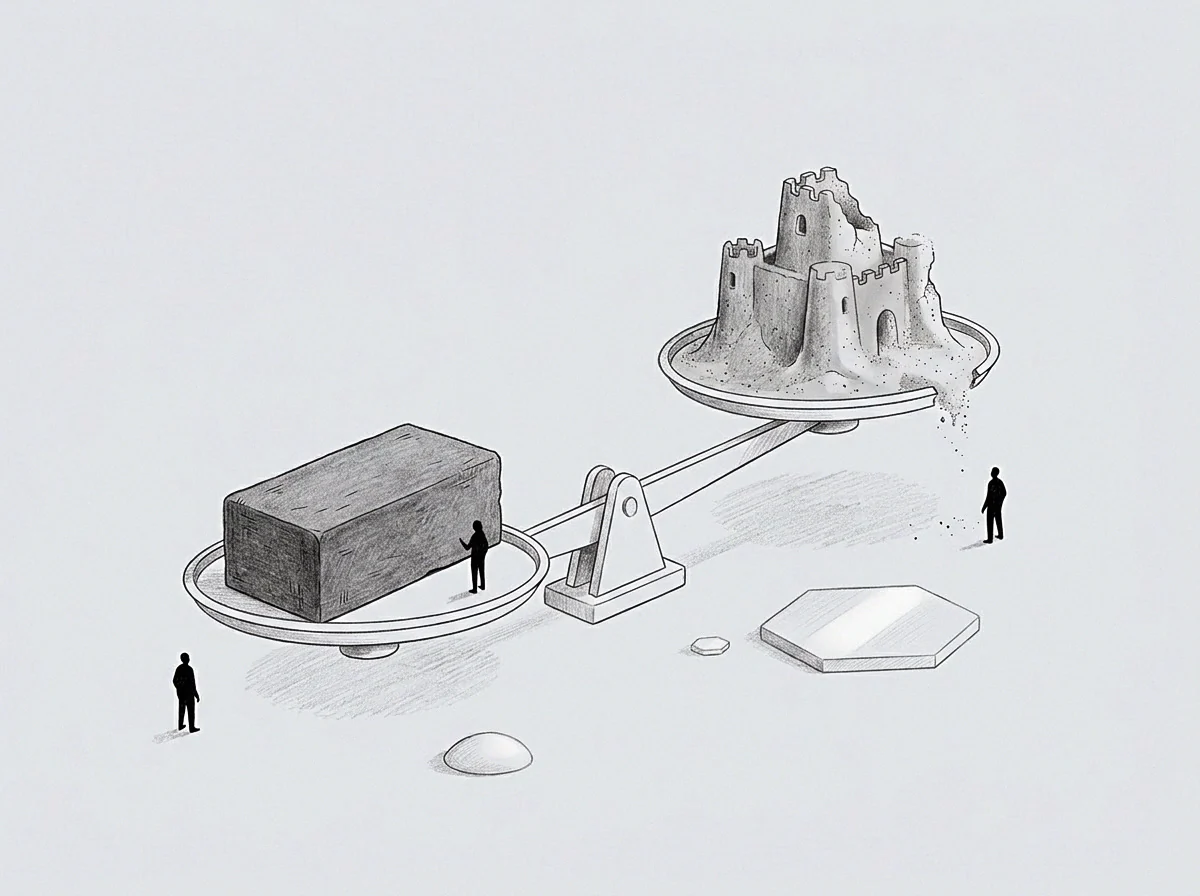
Mathematical and contractual variances between official capitalization registers and actual underlying legal commitments represent fundamental ownership mismatches. These systemic errors emerge within private company registries when equity promises diverge from issued share certificates, option grants, or convertible debt notes. In administrative records, cap table discrepancies describe the measurable delta between spreadsheet records, formal board minutes, share transfer agreements, and promises contained in informal communications.
They measure the integrity of the firm’s capital architecture and define the boundaries of potential equity disputes. The condition ceases to apply once all existing claims are either verified by board documentation or formally waived through signed legal releases.
Origination Dynamics
Clerical errors, informal promises, and unrecorded option exercises frequently destabilise corporate ownership models during rapid operational expansion. A founder may agree in an email exchange to award equity to early personnel without notifying the corporate secretary, or convertible promissory notes may carry contradictory valuation caps across successive financing rounds. Because spreadsheet formulas do not check statutory issuance formalities, informal records drift away from the authoritative minute book.
The presence of cap table discrepancies introduces severe legal uncertainty into later corporate transactions, including private capital raises and strategic sales. This divergence creates competing claims against the same corporate ownership pool.
Reconciliation Procedures
Correcting an erroneous equity ledger requires an exacting line by line audit of historical corporate records, share transfer logs, bank statements, and investor signature pages. Legal advisors must cross-examine informal communications against statutory corporate resolutions, determining which claims possess legal authority and which represent unperfected promises. Resolving these variances often consumes months of management attention, tens of thousands of dollars in accounting fees, and significant negotiating energy to secure retrospective waivers from affected stakeholders.
In severe instances, companies must expand existing equity pools or redistribute ownership shares to avoid costly corporate litigation. The operational disruption diverts leadership focus away from enterprise operations for extensive periods.
Evidentiary Certainty
Definitive share registers must reflect legal reality rather than aspiration, memory, or unratified transactional drafts. Mathematical models of corporate ownership fail when detached from underlying signed contracts and formal board authorisations. The durability of a company’s equity record rests upon the absolute alignment of every ledger entry with a verified, contemporaneous issuance instrument. cap table discrepancies demonstrate that an unrecorded equity commitment remains an ongoing financial and governance risk until it is definitively resolved through corrective corporate action.