

Extinguishing Early Share Promises Before Institutional Venture Rounds
Early verbal share assurances dissolve when founders execute formal legal releases and standardized equity agreements prior to institutional venture rounds.
Early verbal share assurances dissolve when founders execute formal legal releases and standardized equity agreements prior to institutional venture rounds.

Early company equity structures define ownership rights, vesting terms, option pool buffers, and dilution math across capital capitalization tables.

Unratified stock commitments remain unenforceable without formal board authorization, limiting claimants to restitutionary claims for documented services.
Restitution recovers the market value of deferred labor directly from promoters when concealed or unformed corporate charters void limited liability shields.
Verifying charter share capacity confirms authorized unissued shares before executing service agreements, preventing unenforceable stock compensation claims.
An audit of board consents verifies statutory compliance, charter reserves, and formal approval records to identify and cure void or voidable equity grants.
Statutory copyright law leaves unwritten software title with individual authors, requiring signed conveyance deeds to ground corporate equity claims.
Courts assess contemporaneous conduct, tax filings, and unexecuted draft agreements to evaluate the legal definiteness of alleged oral share grant promises.
Sunk reliance costs measure direct out-of-pocket expenses and lost wages incurred when operating under an unfulfilled equity promise in an informal partnership.
Aggrieved venture contributors elect either specific performance for corporate equity or restitution of fair market service value when informal pacts fracture.

Promissory estoppel in early equity disputes requires documented proof of unambiguous share terms, reasonable reliance, and verifiable financial surrender.

Promissory estoppel enforces oral venture equity commitments only when contributors prove measurable detrimental reliance and clear promises despite missing corporate formalities.

Informal co-founder alliances default to statutory individual creator ownership, requiring express written assignments to establish enforceable entity asset boundaries.
Unvested sweat equity converts into retrospective cash wage debts when unwritten equity grants break down under statutory labor standards.
Signed integrated vesting schedules supersede informal chat promises under the parol evidence rule unless explicit written amendments meet board authorization standards.
Unenforceable estoppel equity splits carry transaction holdout leverage through closing representations despite failing statutory board consent requirements.
Liability releases for contested share allocations require distinct economic consideration and explicit statutory waivers to yield clear corporate title before funding.

Written capitalization tables backed by integration clauses extinguish prior informal equity promises by establishing board resolutions as sole ownership records.
Auditing early equity commitments verifies informal share promises against corporate records, extinguishing unrecorded equity claims before enterprise sale closing.
Unwritten co-founder equity disputes resolve by replacing ambiguous historical recollections with objective market valuations and formal contemporary release contracts.
Documenting early ownership splits requires formal board stock authorization, executed restricted stock purchase agreements, and written intellectual property assignments before institutional venture capital diligence begins.

Institutional venture financing resolves unrecorded equity claims through audited diligence, formal releases, and special indemnities that protect incoming capital.

Service providers recover deferred compensation by asserting joint personal promoter liability and restitution against individuals who conceal unfiled charters.
Equity validity depends on active state corporate standing, strict board consent compliance, and share counts remaining inside charter limit caps.

Oral equity commitments require definite terms, mutual assent, and consideration to overcome evidentiary bars under statute of frauds and vagueness doctrines.
Early founder conversations create legally binding terms only when written assent, definite material terms, immediate consideration, and objective mutual intent converge.

Oral equity claims lack structural ground without written board authorization, leaving unpapered builders exposed to total ownership forfeiture.
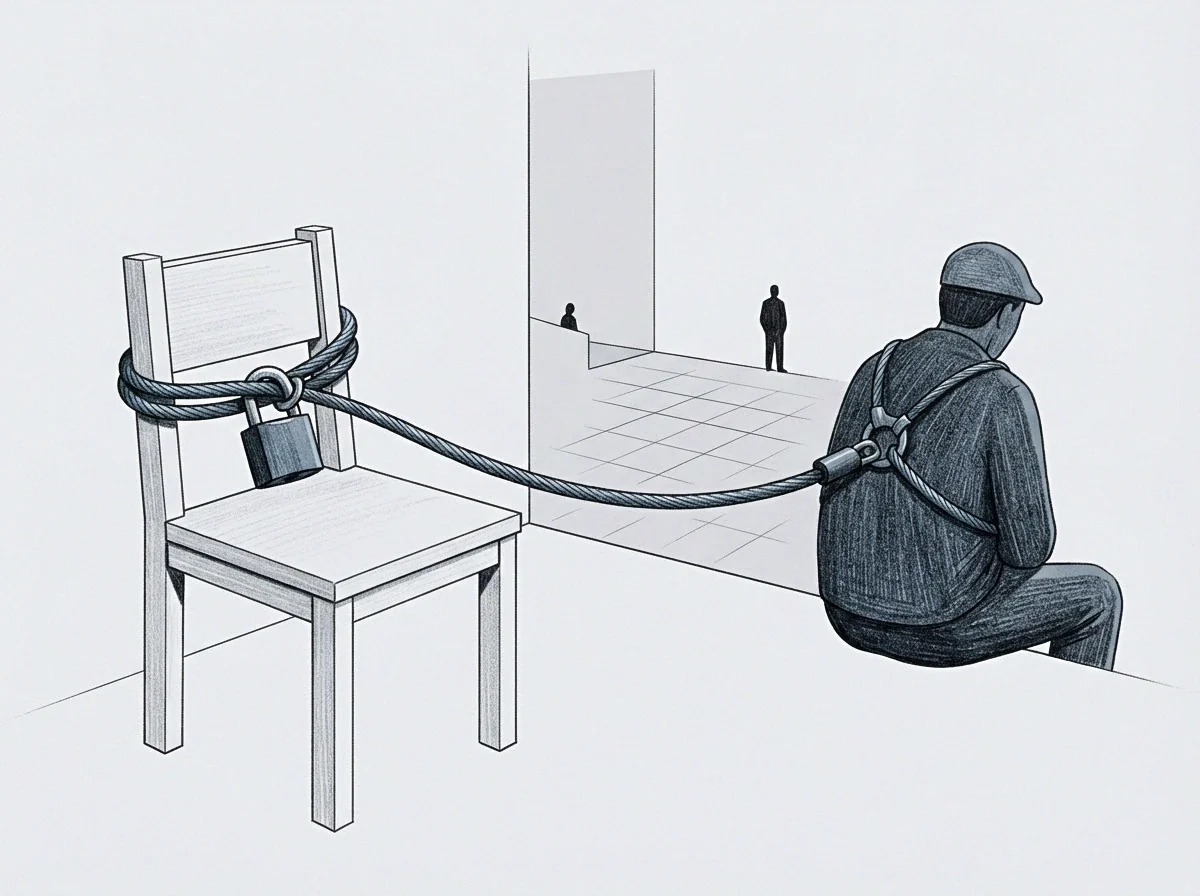
An unfounded claim distributes all operational risk to the executing party while a written instrument anchors legal ownership through verifiable terms.
The terms are written where they belong. Each field holds three desks, and every entry a desk writes raises the terms it uses, each term given a meaning, a mechanism and the places it appears. The record on these pages stays first person and hand made; the fields grow the nomenclature.